Business | Finance | Markets | Technology
Daily analysis of companies, earnings, market movements and important business news.
📈 Data-driven.
🧠 Easy to understand.
📰 Updated daily.
One day after record talk, Wall Street got a bill it did not like.
US stocks fell on Thursday, October 22, as a sharp sell-off in technology and AI shares dragged the Nasdaq down 2.6% — while the Dow, full of banks, insurers and everyday-economy companies, finished almost exactly flat. The split tells the whole story: this was not a bad day for “the market.” It was a bad day for one crowded trade — artificial intelligence spending — and the trigger was Meta’s earnings the night before.
How the Benchmarks Closed
Index
Close
Change
Dow Jones Industrial Average
52,867.98
+0.02%
S&P 500
7,663.43
−1.21%
Nasdaq Composite
26,008.86
−2.60%
Philadelphia Semiconductor Index (SOX)
10,731.98
−6.72%
The semiconductor index fell to its lowest level since July 29, and all 30 of its member stocks declined. When every single chip stock falls together, it is a sector event — not company news.
Why Meta Fell 7% on “Good” Earnings
Meta Platforms reported third-quarter results after Wednesday’s close that beat expectations on the headline numbers:
Revenue: $64.6 billion, up 26% year over year
Reported EPS: $3.83, pulled down by the large one-time legal charge of roughly $10 billion flagged before the report
Q4 revenue guidance midpoint: about $74.5 billion, ahead of the Street’s ~$73.7 billion estimate
So why did the stock fall 6.98% to $648.85 in Thursday’s session?
Because investors stopped reading the income statement and started reading the spending commitments. Meta raised its 2026 capital-expenditure outlook to $135 billion–$145 billion, and disclosed that its total future lease and contractual spending commitments now stand at roughly $825 billion, up from nearly $700 billion disclosed in July. Much of that money is for AI computing power and data centres.
Meta’s credit markets noticed, too. The cost of insuring Meta’s debt (its five-year CDS) jumped to the highest since the contract began trading, and its bonds weakened against US Treasuries. In plain language: lenders are charging Meta more because the company is promising to spend — and possibly borrow — on a scale that now rivals small countries’ budgets.
Comments the same day from Nvidia CEO Jensen Huang about capital constraints in financing the AI buildout added to the nerves: if even Nvidia is talking about the money side of the AI boom, investors reasoned, the spending race is entering a phase where financing — not demand — becomes the question.
Tesla Fell Too — for the Opposite Reason
Tesla reported adjusted earnings of $0.48 per share on revenue of $28.05 billion — better than feared — yet the stock fell 3.08% to $374.58.
The details under the headline explained it: core automotive revenue fell 3% year over year, and energy revenue dropped 16%, which the company linked to lower selling prices and battery supply problems. Tesla also guided 2026 capital spending to roughly $20 billion — lower than expected.
Put Meta and Tesla side by side and the market’s mood becomes clear: on the same night, one giant was punished for promising to spend too much on AI, and the other slipped partly for spending too little. That is what a market looks like when it no longer knows what the “right” amount of AI spending is — it is the definition of a reassessment, and reassessments are volatile.
The Chip Rout, in Numbers
Semiconductors took the hardest hit, continuing a multi-week reassessment of AI spending that has made investors more selective about debt- and equity-funded buildouts:
Nvidia −4.4%
Micron −6.3%
Intel −8.0%
AMD −8.1%
Lam Research −11.8%
Amazon also fell 4.6% ahead of its own earnings next week, and SpaceX gave back 9.1% of Wednesday’s rally.
Where the Money Went Instead
This was a rotation, not a panic. Defensive and everyday-economy sectors rose even as tech fell:
Consumer Staples +3.31%
Utilities +2.07%
Health Care +1.32%
The equal-weight S&P 500 (which counts every stock equally instead of by size) rose 0.73%, beating the main index by almost 2 points
Oil added a second pressure point: Brent crude settled up about 4% at $113.17 a barrel on renewed Middle East escalation fears, even as US Treasury yields posted their biggest drop in more than a year, with the 10-year at about 4.96% — investors buying safe government bonds while selling growth stocks.
What to Watch Next
Friday, October 23: US flash PMI data and consumer sentiment — a check on whether the real economy is as calm as defensive stocks suggest — plus earnings from major energy companies.
Next week is the main event: Amazon, Alphabet, Apple, Microsoft and Nvidia report. After Meta’s reception, every one of them will be asked the same question — how much are you spending on AI, and who is paying for it?
Meta’s $825 billion question: watch whether analysts’ concern stays on spending, or whether Muse AI usage numbers pull attention back to growth.
Sources
TradingKey — “US Stocks Close: Nasdaq Drops 2.6%, SOX Falls Over 6%; Meta Drops 7% After Earnings” (Oct 22, 2026): tradingkey.com
CNBC TV18 — “Asian markets mixed as US tech rally fades” (Oct 22, 2026): cnbctv18.com
TipRanks — “Stock Futures Fall as Investors Assess Meta Platforms and Tesla Earnings” (Oct 22, 2026): tipranks.com
Compiled from public market and company reporting available on October 22–23, 2026. Index levels and prices are Thursday’s closing figures as reported by the sources above; earnings figures are as reported. This article is for information and education only and is not investment advice.
All Eyes on Meta: Today’s Earnings Could Set the Tone for Big Tech
Meta Platforms reports third-quarter 2026 results after today’s closing bell — the first of the “Magnificent Seven” megacaps to report, and the first real test of whether Wall Street’s AI-spending story holds up under its own numbers.
Shares closed Monday at $694.25, against a Wall Street consensus price target of $811.24 and a “Moderate Buy” rating. Tesla reports the same evening, making today the heaviest single day so far this earnings season for AI-linked megacap stocks.
Why Today’s Report Carries So Much Weight
Tech stocks have been on edge for weeks over one question: is the hundreds of billions of dollars Big Tech is pouring into AI data centers actually paying off? The Philadelphia Semiconductor Index fell 15.7% over eight straight sessions earlier this month on exactly that doubt, before chip and AI stocks staged their best single day since late September on Monday, when the Nasdaq Composite jumped 1.11% to 26,430.89.
Meta itself has lived that swing in miniature. The stock was down more than 17% for 2026 about two months ago and has since clawed back to a modest gain for the year, largely on enthusiasm for Muse, the AI agent and model family Meta launched on September 8. Today’s report is where that enthusiasm meets a balance sheet.
Because Meta reports first among the Magnificent Seven, its numbers — and especially its tone on 2026 capital spending — will color how investors read Tesla’s report tonight and the wave of Amazon, Alphabet, Apple, Microsoft, and Nvidia earnings still to come.
What Wall Street Is Expecting
Metric
Estimate / figure
Why it matters
Q3 revenue (consensus)
~$63.34B
Near the high end of Meta’s own $61B–$64B guidance
Q3 adjusted EPS (consensus)
~$6.53–$6.58
A one-time charge (below) could pull reported GAAP EPS toward lower estimates near $5.94
One-time legal charge
~$10B
Tied to a settlement of up to $18B with state attorneys general over youth social-media concerns
Q4 revenue guidance (consensus)
~$73.6B
Sets the bar for the holiday-quarter ad business
FY2026 capex guidance
$130B–$145B
Investors are watching whether Meta raises this range again
Stock price (pre-earnings close)
$694.25
Down from 2026 highs, now up modestly for the year
Consensus price target
$811.24
“Moderate Buy” rating
The biggest focus beyond the headline numbers: whether Meta raises its 2026 capex guidance again, and what usage data it shares on Muse.
What It Means for the Market
Three outcomes are in play tonight. If Meta beats on revenue and holds its capex range steady, expect Monday’s rebound to extend into Thursday’s session, with gains likely spilling into other AI-linked names ahead of their own reports.
If Meta raises its 2026 capex guidance again without matching revenue growth, the AI-spending skepticism that drove the eight-day chip selloff earlier this month could resurface immediately — this time with Meta itself as the trigger rather than a bystander.
The $10 billion legal charge is a wildcard but probably a manageable one. Because Meta disclosed it in advance, most analysts have likely built it into their models already, so a GAAP EPS miss driven purely by the charge is unlikely to be read as an operating problem. A miss on core advertising revenue or a capex surprise would be read very differently.
What to Watch Next
Tonight: Meta’s results land after the 4 p.m. ET close, with Tesla’s following the same evening.
Thursday: Meta’s first trading session after the report — watch whether it drags the Nasdaq with it, up or down.
This week: SpaceX, Netflix, General Motors, GE Aerospace, and Procter & Gamble also report.
Coming days: Amazon, Alphabet, Apple, Microsoft, and Nvidia round out the Magnificent Seven’s earnings run, each likely read against whatever tone Meta sets tonight.
Compiled from public market and company reporting available on October 21, 2026, ahead of Meta’s after-market earnings release. Figures are analyst estimates unless noted as actual, and are subject to change once results are announced. This is not investment advice.
Oil, bond yields, and a Fed that may not be finished raising rates are the forces to watch on Wednesday, October 14.Stocks hold near highs, but the cracks are showingThe major indexes are hovering close to their all-time highs. On Monday, October 12, the S&P 500 closed at about 7,805, the Nasdaq at about 27,204, and the Dow at about 51,670. The S&P had set its first-ever close above 7,800 just days earlier, on October 6. Monday’s moves were small, but the direction was a warning: technology slipped, and chip stocks led the decline.The trigger was news that China’s ChangXin Memory Technologies had made progress on its own memory chip technology. For US investors, that raised a question that matters for years: how much of the chip industry’s lead will last? For a market that has leaned heavily on tech this year, that uncertainty hits hard.**Bank earnings open the season, with mixed results**Earnings season unofficially began Tuesday, October 13, as JP Morgan, Goldman Sachs, Citigroup, and Wells Fargo reported before the open. Reactions were mixed, and the market had no clear direction early in the session. Bank results matter beyond banking. They offer a read on lending, consumer health, and how companies are handling higher borrowing costs.Bond yields are doing the Fed’s workThe 10-year Treasury yield, the benchmark for mortgages and auto loans, hovered around 5.19% on Tuesday morning, after touching its highest level since 2002 earlier in the month. Fed Governor Christopher Waller said higher yields are already slowing demand in rate-sensitive areas. In other words, the bond market may be tightening conditions on its own.Fed officials are still divided on what comes next. New York Fed President John Williams said he still sees one more rate hike as appropriate this year, but doesn’t think another one will be needed in 2027. That’s the kind of comment that can move markets quickly, and it’s why bond yields fell modestly after his remarks.**Oil remains the wild card**Crude oil has been a source of anxiety all week. WTI crude was around $92.50 a barrel on Tuesday morning, slightly lower after a recent surge. Higher oil feeds into gas prices, transportation costs, and eventually the prices of goods Americans buy every day. That’s why oil and inflation are linked in investors’ minds.**Today’s catalyst: the CPI report**The consumer price index is the main economic release today. It measures how much prices have risen for everyday goods and services. A hotter-than-expected reading could push yields higher and keep pressure on the Fed to stay tight, which would weigh on tech and interest-sensitive sectors. A cooler reading could ease yields and give stocks some breathing room.**What this means for you**Stocks are near records, but they’re being held up by strong expectations for tech and earnings, while higher yields and oil prices make the outlook less certain. If you’re buying a home, refinancing, or taking on a car loan, today’s inflation report and the trend in bond yields matter more than the daily stock index moves. If you invest for the long term, the short-term swings are less important than whether your portfolio matches your timeline and risk tolerance.**What to watch next**Today’s CPI reading, the rest of this week’s bank earnings, and any new Fed signals. Also watch the chip sector. If the CXMT news turns into a lasting shift in confidence, it could reshape the tech trade.*This is general information, not investment advice.*
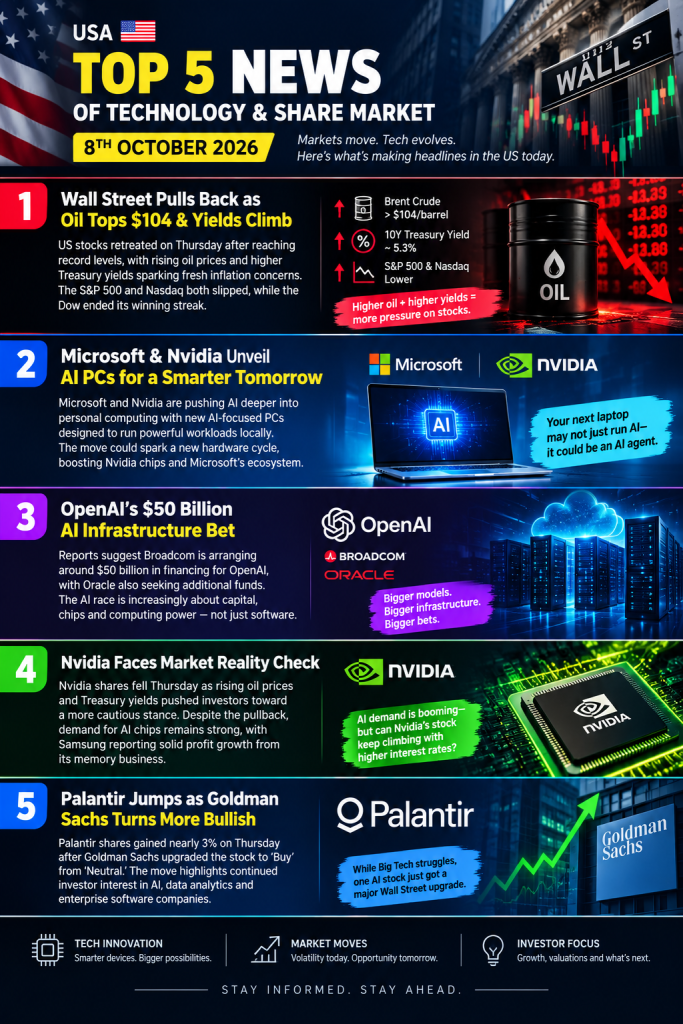
Today’s U.S. market story is basically “AI optimism meets higher interest rates, expensive oil, and rising financing costs.” The major indexes have recently been near record levels, but investors are becoming more cautious. (AP News)
1. 📉 Wall Street pulls back from record highs
U.S. stocks retreated today after recently reaching records. The S&P 500 fell about 0.4%, the Dow about 0.4%, and the Nasdaq about 0.5% during Thursday trading. Nvidia also slipped around 0.6%. (AP News)
Why is this happening?
The biggest concern is a combination of:
Higher oil prices
Rising U.S. Treasury yields
Persistent inflation concerns
Expectations that interest rates could remain high
Geopolitical uncertainty surrounding Iran and Middle East energy supplies
The 10-year U.S. Treasury yield moved around 5.27%–5.35%, levels not seen since the early 2000s. Higher yields can make stocks—particularly expensive growth and technology stocks—less attractive because investors can earn more from relatively safer bonds. (AP News)
Investor takeaway: The long-term AI story hasn’t disappeared, but today’s market shows that macroeconomic factors can temporarily overpower AI enthusiasm.
2. 🤖 AI companies are borrowing billions to build AI infrastructure
One of the most important technology-finance stories today is the enormous amount of money being raised to fund AI infrastructure.
Reports indicate that companies including SpaceX, Broadcom and Oracle are pursuing very large financing arrangements to acquire AI chips and build data-center capacity. Broadcom is reportedly arranging more than $50 billion related to custom AI chips being developed with OpenAI, while SpaceX is seeking around $40 billion to finance Nvidia chips. (The Wall Street Journal)
This is significant because the AI boom is moving beyond software.
The new investment cycle is increasingly about:
AI models → GPUs → data centers → electricity → networking → cooling → financing
That means companies involved in AI infrastructure can potentially benefit even if they aren’t selling an AI chatbot directly.
But there’s also a risk: companies are taking on enormous amounts of debt to finance rapidly changing technology. If AI demand grows as expected, these investments could generate huge returns. If demand disappoints, companies could be left with expensive infrastructure and debt.
Investor takeaway: AI is becoming not just a software story but a massive capital-investment story.
3. 💻 Microsoft launches a major push toward on-device AI
Microsoft is pushing AI deeper into personal computers.
Microsoft unveiled a new high-performance Surface Ultra laptop using Nvidia’s RTX Spark technology. The broader strategy is to make PCs capable of running more sophisticated AI locally rather than sending every task to cloud data centers. (Reuters)
Microsoft is also introducing technology designed to control what AI agents can access on a computer, addressing an important problem: AI agents need permissions and security boundaries if they are going to perform tasks autonomously.
This could create a new competitive battlefield:
Apple vs Microsoft vs Nvidia vs Intel vs AMD
The traditional PC was primarily about CPU performance. The emerging AI PC market is increasingly about CPU + GPU + AI acceleration + local models + AI agents.
For Nvidia, entering this market could be particularly important because Intel and AMD have historically been dominant in PC processors. (Reuters)
Investor takeaway: AI may gradually change the PC from a device where users operate software into a device where AI agents perform tasks for users.
4. 🧠 Nvidia-backed startup wants different AI chips to work together
Another interesting infrastructure development today involves Upscale AI, a startup backed by Nvidia.
The company launched Token Fabric, a platform designed to allow data centers to connect AI processors from different chip manufacturers more easily. (Reuters)
Why does this matter?
Today’s AI infrastructure is highly complex. A data center might contain processors from different vendors, each with different networking and software requirements.
If companies can combine different AI chips more efficiently, they may have greater flexibility rather than becoming completely dependent on one supplier.
The potential result is:
More chip choices → easier data-center deployment → potentially lower infrastructure complexity → greater AI computing capacity
This is particularly interesting because Nvidia currently has enormous influence over the AI accelerator market.
Investor takeaway: The next phase of AI competition isn’t only about who makes the fastest chip. It is also about who controls the infrastructure connecting thousands of chips together.
5. 🏭 AI chip and data-center stocks face a reality check
AI-related stocks have been among the biggest winners of the market’s recent rally, but today investors are becoming more selective.
Stocks including Intel, Marvell, Micron, Coherent, Corning and Dell came under pressure as higher yields and renewed inflation worries interrupted the AI-driven rally. At the same time, some individual AI-related companies continued to attract investors. (Barron’s)
One notable exception was Applied Digital, a data-center company benefiting from AI demand. Its revenue reportedly jumped more than 320% year over year, highlighting how quickly demand for AI infrastructure is translating into actual business growth. (Barron’s)
Another interesting move was Wolfspeed, which surged after securing a $1.5 billion, 30-year financing agreement with the U.S. Department of Defense connected to domestic silicon-carbide production. (Barron’s)
This illustrates an important theme: America’s AI and technology strategy increasingly involves domestic semiconductor and advanced-material supply chains.
📊 What today’s news means for investors
Theme
Current signal
Why it matters
🇺🇸 S&P 500
⚠️ Pullback
Record valuations face higher yields
💻 Nasdaq/Tech
⚠️ Under pressure
Growth stocks sensitive to interest rates
🤖 AI
🟢 Strong
Infrastructure spending remains enormous
🧠 Nvidia
🟢 Long-term AI leader, but volatile
Chips remain central to AI expansion
🏢 Data centers
🟢 Strong demand
AI requires enormous computing capacity
💰 AI financing
⚠️ Increasing risk
Massive debt is funding infrastructure
🛢️ Oil
🔴 Rising sharply
Could increase inflation
📈 Treasury yields
🔴 Very high
Makes bonds more competitive with stocks
🎯 The big picture
The most important story today isn’t simply “stocks are falling.”
It’s this:
The AI boom is getting bigger, but it is also getting more expensive to finance.
The U.S. technology market is entering a stage where investors will increasingly ask two questions:
1. How much money can AI generate? 2. How much does it cost to build the infrastructure needed to generate it?
That tension between AI growth and financing costs is likely to remain one of the biggest themes for U.S. technology stocks.
This is market news and analysis, not a recommendation to buy or sell any security.
Tesla delivered 486,532 vehicles in Q3 2026 — beating Wall Street’s own compiled consensus of 461,974 by roughly 5.3% (about 24,500 extra vehicles). It also produced over 464,000 vehicles and deployed 13.7 GWh of energy storage products.
Model 3/Y
Other Models
Total
Production
457,387
7,004
464,391
Deliveries
478,237
8,295
486,532
Why It’s “Rippling,” Not Just a One-Day Story
1. It defied the bears. Heading into the report, most analysts — UBS, Goldman Sachs, Visible Alpha — expected a year-over-year decline, some forecasting drops as steep as 5-7% from Q3 2025’s record 497,099. Instead, deliveries came in down just ~2.1% YoY and actually up 1.3% from Q2 2026. That’s a meaningfully better outcome than the Street had priced in.
2. It extends an unusual pattern. This marks Tesla’s second straight quarter of blowing past consensus — Q2 2026 beat estimates by a staggering 18%. The market is now recalibrating how much credibility to give Tesla’s own compiled “analyst consensus” figure versus the eventual actual result.
3. History says the stock reaction is unpredictable. This is the part making it a genuine talking point: in Q2 2026, Tesla beat estimates by 18% and its stock still fell 7.5% the same day — a classic “sell the news” move, since much of the good news was already priced in given Tesla’s valuation. Whether Q3’s beat triggers a similar shrug or an actual rally has been a live debate among traders this week.
4. The real catalyst is still ahead. Delivery numbers are just a volume count — they say nothing about profitability. The number that will actually move the stock meaningfully is Tesla’s full Q3 financial report, due October 21, 2026 (after market close, with a management call at 5:30 PM ET). That report will reveal margins, profit, and — critically — forward guidance on Full Self-Driving (FSD), the Cybercab, and robotaxi progress, which is what Tesla’s premium valuation is really betting on.
The Bigger Picture
Tesla trades at a valuation that assumes it’s far more than a car company — investors are pricing in AI, autonomy, and robotics ambitions. That’s why a genuinely strong delivery beat can still leave the stock flat or down: the market isn’t just asking “did Tesla sell more cars?” — it’s asking “is the AI/autonomy story still on track?” October 21 is where we’ll get a real answer.
Broadcom’s blockbuster quarter set the stage. Reporting fiscal Q3 2026 results, Broadcom posted revenue of $29.6 billion (up 86% year-over-year) and guided Q4 revenue to $34.8 billion — with $21.7 billion of that specifically from AI semiconductors, up 236% year-over-year. CEO Hock Tan raised full-year AI revenue guidance to $58 billion (from $56 billion), a 186% YoY increase.
The headline detail: Google’s new TPU chip. During the quarter, Broadcom began production shipments of Google’s next-generation AI chip, the TPU v8i, and said it will ramp to high-volume shipments in Q4 (the quarter we’re in right now). Tan noted this chip — designed with more memory and bandwidth than its predecessor — is shipping ahead of a competing chip from MediaTek, and is “the same or better than Nvidia’s Vera Rubin” (Nvidia’s next flagship AI chip).
It’s not just Google. Broadcom is also ramping:
High-volume Ironwood TPU v7 shipments to both Google and Anthropic
Meta’s custom MTIA accelerator chip, expected to hit production scale in Q4
Anthropic specifically is expected to deploy 5 additional gigawatts of TPU v8i capacity in 2027, which Broadcom’s CEO says could make Anthropic “our largest XPU customer”
Broadcom’s CEO projected AI revenue will double to ~$115 billion in 2027, and double again to ~$230 billion in 2028.
Why Marvell’s Investor Day (Today) Matters
Marvell is a smaller but important player in this same custom AI chip ecosystem — it designs the specialized connectivity and custom silicon that hyperscalers (Google, Amazon, Microsoft) use to build their own AI chips rather than relying solely on Nvidia. Marvell’s Q2 FY2027 results, reported in late August, showed:
Revenue of $2.74 billion, up 37% YoY
Data center revenue up 46% YoY
Raised outlook for 2027-2028
Analysts have been specifically waiting for today’s Investor Day because Marvell has an expanding relationship with Google that management hinted would become “a significant contributor” starting in 2028 — but held back details for exactly this event. It’s expected to be similar to Marvell’s 2025 “Custom AI Investor Event,” where it laid out a multi-year silicon and revenue forecast.
Why This Matters for the Broader Market
This is the mechanism behind the “AI infrastructure supercycle” driving the stock market highs I mentioned earlier:
Hyperscalers (Google, Amazon, Meta, Microsoft) are increasingly building their own custom AI chips instead of only buying Nvidia GPUs — partly for cost control, partly because Nvidia itself has said it’s capacity-constrained.
Broadcom and Marvell are the two companies that actually design and supply this custom silicon, which is why their results function almost as a “pulse check” on the entire AI buildout.
Every beat-and-raise quarter from these companies reinforces the market’s confidence that AI capex isn’t slowing down — which is a major reason the Nasdaq and S&P 500 keep hitting records.
The flip side, as I mentioned before: this also means a lot of the market’s strength is riding on the assumption that this chip-ramping pace continues without disruption — any sign of a slowdown in hyperscaler spending would hit these stocks (and the broader market) hard.
On September 2, 2026, President Trump signed a Continuing Resolution (CR) — officially the Continuing Appropriations and Extensions Act, 2027 (H.R. 6500) — that keeps the federal government funded at current (FY2026) levels through December 11, 2026. It passed with strong bipartisan support: 90-6 in the Senate, 370-48 in the House. That’s a notably lopsided, non-partisan vote for Washington these days, which tells you both parties wanted to avoid a third shutdown badly.
Why This Matters — The Backdrop
This isn’t happening in a vacuum. 2026 has already been a brutal year for government funding:
A 43-day shutdown ran from October 1 to mid-November 2025, after the previous Congress failed to agree on FY2026 funding.
A 76-day partial shutdown of the Department of Homeland Security ran from mid-February to early May 2026, tied to a dispute over immigration enforcement funding.
Combined, parts of the government were shut down for roughly 161 days — about 44% of the fiscal year. That’s an extraordinary amount of dysfunction, even by Washington standards.
So when September 30 rolled around again as the next hard deadline, there was real fear of a third closure — made worse by the fact that November 2026 midterm elections were right around the corner, which usually makes Congress more gridlocked, not less.
What’s Actually In the Deal
Funding stays flat at FY2026 levels — no new spending increases, essentially a “pause” rather than a resolution.
WIC (the nutrition program for low-income women, infants, and children) gets targeted funding adjustments to keep it running.
Shipbuilding and national security programs get protected funding.
The Disaster Relief Fund is funded, which matters for FEMA’s ability to respond to hurricanes, wildfires, etc.
Defense funding stays at FY2026 levels with a key restriction: no new weapons programs or multiyear contracts can start — this is standard CR boilerplate, but it specifically avoided a scenario where troops would work without pay or civilian defense employees would be furloughed.
Notably excluded: White House-requested funding for an Iran war supplemental and a $1 billion Trump-class battleship program — Democrats specifically pushed back on these.
A regulatory provision delays an OMB rule (the “Uniform Guidance” overhaul affecting how federal grants are administered) until December 11 — a relief for universities, research institutions, and nonprofits worried about new red tape.
Democrats also say they closed a loophole that would’ve let the administration shift money from other programs into Border Patrol funding without additional reform.
What This Means for You, Practically
Right now: nothing is disrupted. Federal agencies are open, federal employees are being paid, Social Security and Medicare are unaffected (these aren’t subject to annual appropriations anyway), national parks are open, and routine government services (passports, IRS, etc.) are operating normally.
If you’re a federal employee or contractor: this CR is specifically designed to avoid furloughs and pay disruptions through December 11 — but that protection expires on that date if Congress doesn’t act again.
If you rely on WIC or disaster relief programs: funding is protected through this window.
The real deadline to watch is December 11, 2026. Congress now has to use this window to negotiate actual full-year FY2027 appropriations bills — not just another stopgap. Given the House and Senate are still disagreeing over overall funding levels and defense spending specifics, there’s no guarantee a clean deal happens by then, and given this year’s track record (two
Think of this less as “the funding problem is solved” and more as “Congress bought itself ten extra weeks to avoid blame for a shutdown right before the midterms.” The underlying disagreements — overall spending levels, defense priorities, immigration enforcement funding — haven’t been resolved, just postponed. December 11 is the next real test of whether Washington can pass a full-year budget or whether 2026 ends the way it largely played out: funded in fits and starts.
For context on how far this run has come: the Dow crossed 50,000 for the first time this year, and the Nasdaq has repeatedly set fresh records through 2026, even after a rough patch earlier in the year.
What’s Driving It
1. The AI infrastructure supercycle. This is the dominant story of 2026 markets. Hyperscalers — Microsoft, Google, Amazon, Meta — have collectively guided to roughly $650 billion in capital expenditures for 2026, almost all aimed at AI data centers and chips. That spending has flowed directly into the stocks building the infrastructure:
Nvidia reclaimed the title of world’s most valuable public company in July 2026, with a market cap around $4.86 trillion, after Jensen Huang revealed Nvidia had overtaken Apple as TSMC’s biggest customer.
Broadcom has been riding both its own AI accelerator business and a reported $10B chip deal to help OpenAI build custom AI chips.
Micron reportedly joined the “$1 trillion club” on surging AI-memory demand.
Chip/AI-infrastructure names like Marvell continue to be a focal point (its Investor Day is today).
2. Sector rotation. Energy and technology have been the best-performing sectors recently; healthcare, real estate, and utilities have lagged — the latter two likely pressured by elevated bond yields making rate-sensitive sectors less attractive.
The Undercurrent of Risk
Nearly every write-up of this rally carries the same caveat: valuations are stretched, and there’s genuine debate about whether this is a sustainable AI-driven re-rating of the economy or a bubble.
The 10-year Treasury yield has been sitting high (~5.2%), which is unusual alongside record equity highs and adds pressure on rate-sensitive sectors.
Earlier in 2026, the Nasdaq actually fell into a 10% correction, driven by conflict-related oil price spikes and monetary policy uncertainty — a reminder the rally hasn’t been a straight line up.
Analysts frequently flag that AI capex is effectively propping up headline GDP and market breadth, meaning a lot of this market’s strength is concentrated in a fairly narrow set of mega-cap tech/AI names rather than being broad-based.
The market is near record highs almost entirely on the strength of an AI infrastructure spending boom among a handful of giant tech companies, with chipmakers (Nvidia, Broadcom, Micron) and cloud hyperscalers as the main engines. The risk flagged consistently by strategists is valuation: if AI capex growth slows, or earnings don’t catch up to the optimism priced into these stocks, the pullback could be sharp — as the earlier-2026 correction already demonstrated.
One important correction first: the statement that Anthropic is “targeting 5 GW by the end of 2026” is too broad. Anthropic has secured up to 5 GW of new AWS capacity, but its own announcement says nearly 1 GW of Trainium2/Trainium3 capacity is expected to come online by the end of 2026; the broader 5-GW commitment is a longer-term infrastructure expansion.
1. What is the “AI chip race”?
Think about AI development as a chain:
AI models → computing → AI chips → servers → networking → data centers → electricity + cooling
Companies such as Anthropic, OpenAI and Google are competing to build increasingly powerful AI models.
But there is a problem:
The better the AI model becomes, the more computing power it generally needs.
That means the companies cannot simply write better software. They also need massive amounts of hardware.
And this is why the chip race has become one of the biggest stories in technology and markets.
2. Why NVIDIA is no longer the entire story
For years, the simplified AI-chip story was:
AI → NVIDIA GPUs
NVIDIA remains enormously important, but AI companies increasingly want alternatives and customization.
Why?
Because relying entirely on one type of accelerator can mean:
high costs
limited supply
power inefficiency for particular workloads
dependence on one supplier
less control over hardware/software optimization
So the industry is moving toward a much more complicated ecosystem.
The emerging landscape
Company
Strategy
NVIDIA
General-purpose AI accelerators + networking
AMD
Alternative AI accelerators
Google
Custom TPU accelerators
Amazon/AWS
Trainium custom AI chips
Broadcom
Custom AI accelerator design + networking
OpenAI
Developing its own AI accelerators
Anthropic
Using multiple chip platforms
Microsoft
AI infrastructure + custom silicon/cloud ecosystem
The important trend is:
AI companies are becoming increasingly involved in designing the hardware they run on.
3. Anthropic: the “5 GW” story
This is one of the most important parts.
Anthropic has dramatically increased its computing ambitions.
In April 2026, Anthropic and Amazon announced an agreement for up to 5 gigawatts of new compute capacity for training and deploying Claude.
Anthropic says the commitment involves more than $100 billion over ten years in AWS technologies. (Anthropic)
But here’s the important distinction:
5 GW ≠ 5 GW online by December 2026.
Anthropic said that nearly 1 GW of Trainium2 and Trainium3 capacity is expected to come online by the end of 2026. (Anthropic)
Anthropic is also diversifying its hardware.
It currently uses:
AWS Trainium + Google TPUs + NVIDIA GPUs
rather than relying exclusively on one chip platform. (Anthropic)
4. Why 5 GW is such a huge number
Most people hear 5 gigawatts and don’t immediately understand what it means.
Think of it as an enormous amount of continuous electrical capacity dedicated to computing infrastructure.
AI data centers aren’t just warehouses full of computers.
They require:
AI chips ↓ Servers ↓ Networking ↓ Cooling ↓ Power infrastructure ↓ Data-center buildings
So when Anthropic says it needs gigawatts of compute capacity, the implications extend far beyond semiconductor companies.
It creates demand for:
GPUs
custom accelerators
HBM memory
networking chips
optical networking
servers
transformers
power systems
cooling equipment
data centers
electricity generation
cloud infrastructure
That’s why the AI boom is increasingly being described as an infrastructure buildout.
5. Anthropic is also betting on Google TPUs
Anthropic isn’t putting all its chips in Amazon’s basket.
In April 2026, Anthropic announced a separate agreement with Google and Broadcom for multiple gigawatts of next-generation TPU capacity, expected to begin coming online in 2027. (Anthropic)
This is strategically important.
Google designs its own AI accelerators called TPUs — Tensor Processing Units.
In October 2025, OpenAI and Broadcom announced a collaboration to deploy 10 gigawatts of OpenAI-designed AI accelerators.
The systems are targeted to begin deployment in the second half of 2026, with deployment continuing through 2029. (Broadcom Inc.)
This is a massive strategic shift.
OpenAI isn’t simply saying:
“Give us more GPUs.”
It is effectively saying:
“We want to help design the computing infrastructure that powers our models.”
7. Why Broadcom is suddenly extremely important
This is where your earlier AI infrastructure story connects directly.
Broadcom isn’t primarily known by consumers like NVIDIA is.
But it sits underneath a huge part of the AI infrastructure ecosystem.
Broadcom works on:
custom AI accelerators
networking
Ethernet
connectivity
data-center infrastructure
The OpenAI partnership involves both AI accelerators and networking systems. (Broadcom Inc.)
So Broadcom represents an important trend:
Hyperscalers and AI labs increasingly want custom silicon.
Instead of buying a completely standardized processor, a company can work with a chip designer to create hardware optimized for its particular workload.
8. What does “custom AI chip” actually mean?
Imagine two cars.
NVIDIA GPU
Like a high-performance sports car that can perform many different jobs.
It is extremely powerful and flexible.
Custom AI accelerator
More like a specialized racing car designed for one particular type of track.
It may not be as flexible, but it can potentially deliver:
This becomes extremely important when you’re operating millions of AI queries every day.
Even a small efficiency improvement can become worth billions of dollars at massive scale.
9. OpenAI’s custom chip is already more than just a future idea
This is another place where the original wording needs updating.
OpenAI unveiled its first custom AI chip, designed with Broadcom, in June 2026.
The chip, called Jalapeño, is designed specifically for AI inference—the stage where a trained model actually processes a user’s request and produces an answer.
So OpenAI’s hardware strategy has moved from:
“We might make chips someday.”
to:
“We are actually designing and deploying custom silicon.”
That is a major development.
10. Where does Google fit?
Google is one of the most vertically integrated players in AI.
It has:
AI models → Gemini
AI chips → TPUs
Cloud → Google Cloud
Data centers → Google infrastructure
Applications → Search, Workspace, Android, etc.
That gives Google something many AI startups don’t have:
Control over almost the entire AI stack.
And Anthropic’s growing use of Google TPUs makes Google’s chip business even more strategically important. Anthropic previously announced plans to expand to as many as one million Google TPUs, with more than 1 GW expected to come online in 2026. (Anthropic)
11. This creates a fascinating three-way competition
Even companies developing custom chips continue to use NVIDIA GPUs.
Anthropic explicitly says it uses AWS Trainium, Google TPUs and NVIDIA GPUs. (Anthropic)
And AWS and NVIDIA announced in August 2026 that AWS plans to deploy 2 million additional NVIDIA GPUs across its global infrastructure. (US Press Center)
So the story isn’t:
Custom chips will kill NVIDIA.
It’s more accurately:
The AI accelerator market is becoming more diversified.
NVIDIA can remain dominant while Google TPUs, AWS Trainium and custom ASICs take specific workloads.
13. The real battle: cost per AI query
This is perhaps the most important concept for understanding the next stage.
Training a model is expensive.
But once millions or billions of people use that model, inference costs become enormous.
Having money to build an AI data center doesn’t help if you can’t get enough electricity to operate it.
🎯 The simplest way to explain the entire story
The AI race is no longer just about building smarter models. It’s becoming a race to build enough computing capacity—and to make that computing cheaper, faster and more energy-efficient.
Anthropic is expanding across AWS Trainium, Google TPUs and NVIDIA GPUs, including an agreement for up to 5 GW of AWS capacity, while OpenAI is moving toward 10 GW of custom accelerators with Broadcom; meanwhile, Google continues developing its own TPU ecosystem. (Anthropic)
“The next AI winner may not simply be the company with the smartest model—it may be the company that can run intelligence at the lowest cost and at the largest scale.”
That is the real story behind the Anthropic–OpenAI–Google chip race.
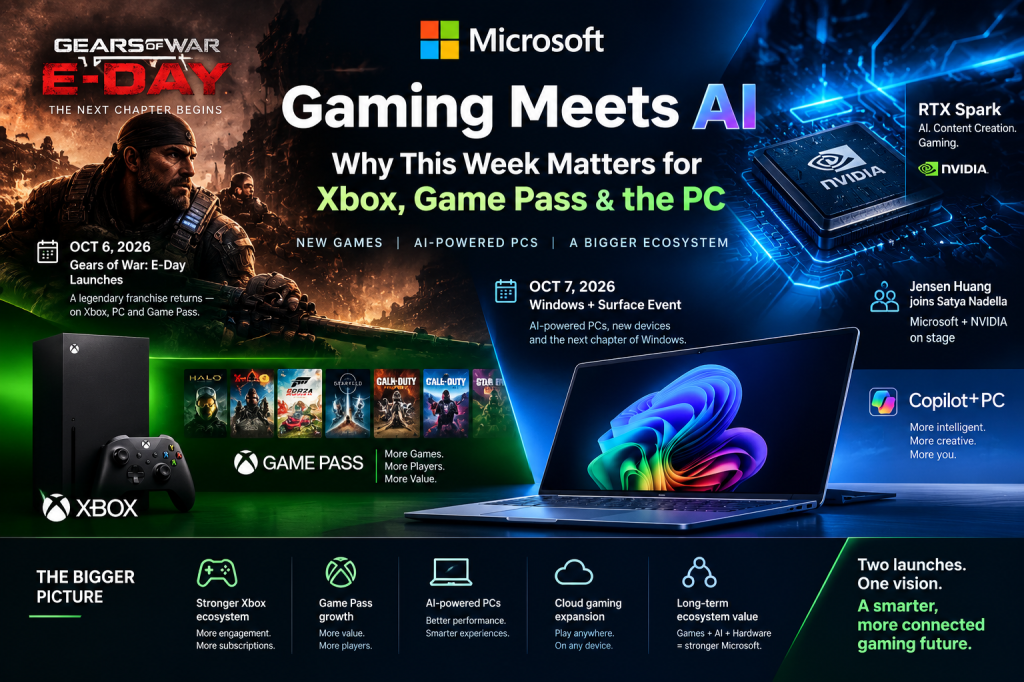
If you’re building your daily market/news blog, Microsoft’s gaming story this week is worth covering because it combines a major Xbox release with Microsoft’s broader gaming + AI strategy.
🎮 1. Gears of War: E-Day launches October 6
Microsoft/Xbox is releasing Gears of War: E-Day on October 6, 2026 for Xbox Series X|S and PC, with Xbox Play Anywhere and Game Pass support. Xbox describes it as an origin story set 14 years before the original Gears of War, centered on Marcus Fenix and the beginning of the Locust invasion. (XBOX Wire)
This is important because Gears of War is one of Xbox’s flagship franchises, so the launch gives Microsoft an opportunity to drive engagement across consoles, PC and Game Pass.
💰 2. Why investors should care
The interesting part isn’t simply the game release.
Microsoft’s gaming business is increasingly being built around an ecosystem:
Game → Xbox → PC → Game Pass → Cloud Gaming → recurring engagement
That means a major first-party release can potentially increase:
Game Pass subscriptions
Xbox engagement
PC gaming activity
Digital game sales
Cloud gaming usage
Long-term franchise value
🤖 3. Then comes Microsoft’s October 7 event
Just one day after the Gears launch, Microsoft has its Windows + Surface event on October 7.
This isn’t primarily a gaming event, but it is highly relevant to Microsoft’s broader AI + gaming ecosystem.
Microsoft and NVIDIA are expected to highlight RTX Spark, with NVIDIA CEO Jensen Huang joining Microsoft CEO Satya Nadella. RTX Spark is designed for AI, content creation and gaming, and NVIDIA says it can deliver AAA gaming at 1440p with more than 100 FPS under specified configurations. (NVIDIA Investor Relations)
🔥 The bigger story
So your blog can frame this as more than “Microsoft launches a game.”
It’s:
Microsoft is pushing two sides of the future PC ecosystem in the same week — blockbuster gaming on October 6 and AI-powered Windows hardware on October 7.
That makes this a particularly good story for your Business + Tech + Markets profile.